Canada proposes RRSP-for-life plan to eliminate RRIF conversion rules
Budget 2026 introduces an innovative RRSP-for-life model designed to eliminate mandatory RRIF conversions, merging retirement accounts into a single continuous vehicle.
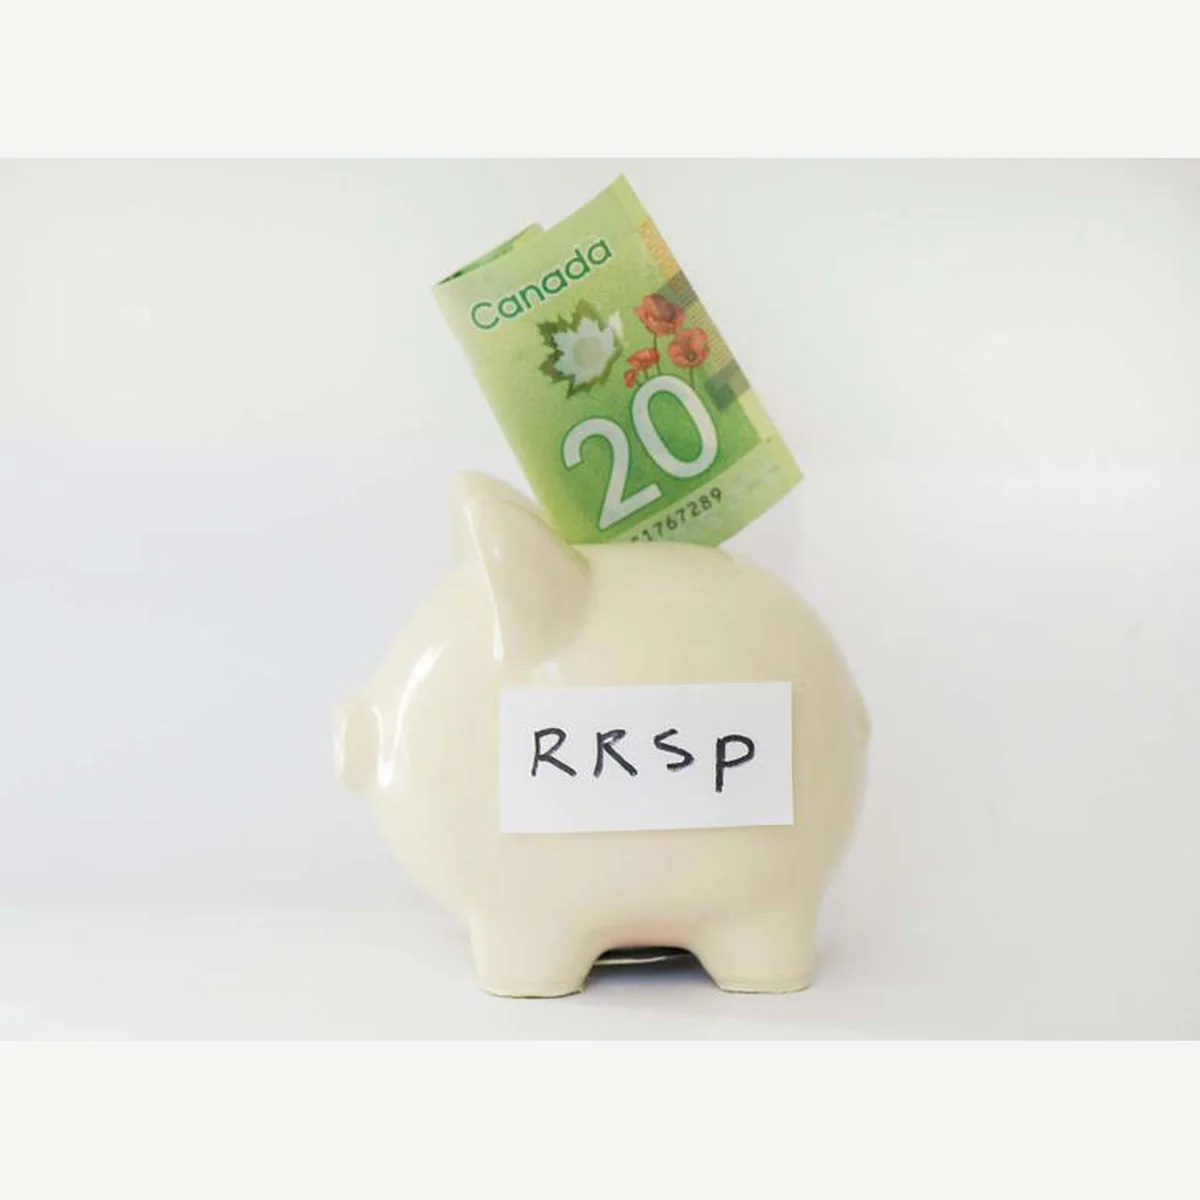
- Core Development: Budget 2026 introduces an innovative RRSP-for-life model designed to eliminate mandatory RRIF conversions, merging retirement accounts into a single continuous vehicle.
- Beat Context: Categorized under Business with independent corroboration.
- Reporting Depth: 3 minute analytical read synthesized from verified newsroom sources.
Canada is preparing to overhaul how its citizens manage their retirement nest eggs. The federal government has proposed an innovative “RRSP-for-life” plan designed to eliminate mandatory conversion rules that have long governed older savers, according to recent financial reporting. Unveiled by Finance Minister François-Philippe Champagne in Budget 2026 on November 5, 2026, the sweeping proposal merges Registered Retirement Savings Plans (RRSPs) and Registered Retirement Income Funds (RRIFs) into a single, continuous account.
Under current regulations, Canadians face a strict administrative deadline. By December 31 of the year they turn 71, account holders must settle their RRSP arrangements by either purchasing an annuity, withdrawing the full balance subject to income tax, or converting the savings into a RRIF. The newly proposed model aims to eradicate this forced conversion step, allowing savers to maintain one unified retirement vehicle throughout their lives, as outlined by Swikblog.
Media additions


Despite the structural simplification, the core obligation of drawing down funds remains unchanged. Retirees would still be required to initiate minimum annual withdrawals starting in the year they turn 72. For instance, under current RRIF parameters, the minimum withdrawal rate at age 72 sits at 5.40 per cent, meaning an account holder with $200,000 in savings would withdraw at least $10,800. Furthermore, contribution limits would remain tied to the existing age restriction, capping personal contributions at the end of the year an individual turns 71.
Tax experts and financial planners have weighed in on the administrative versus financial nature of the proposal. Jamie Golombek, managing director of tax and estate planning at CIBC Private Wealth, noted that the concept allows an account holder to retain a single retirement vehicle until death or assign a successor. Adam Chapman, a certified financial planner based in London, Ont., told The Globe and Mail that the overhaul represents a significant improvement to the system's mechanics, though he cautioned that the benefits would skew toward younger generations rather than baby boomers.
| Retirement Element | Current System (RRSP / RRIF) | Proposed "RRSP-for-Life" Model |
|---|---|---|
| Account Structure | Separate RRSP and RRIF accounts | Combined single retirement account |
| Conversion at Age 71 | Mandatory conversion to RRIF or annuity | Eliminated |
| Mandatory Withdrawals | Required starting at age 72 (based on RRIF rules) | Required starting in the year turning 72 |
| Maximum Contribution Age | End of the year turning 71 | End of the year turning 71 |
The proposal also addresses estate planning and survivor benefits. Ottawa is considering allowing a surviving spouse or common-law partner to act as a "successor holder" of an RRSP, mirroring existing rules for RRIFs and Tax-Free Savings Accounts (TFSAs). Simon Wong, head of financial planning at Blueprint Financial, emphasized that the primary victories are administrative rather than monetary. Meanwhile, Jason Heath, managing director at Objective Financial Partners, suggested that combining the accounts could eventually pressure financial institutions to eliminate routine administration fees associated with RRSP withdrawals.
Skepticism remains regarding how existing tax benefits will map onto the new structure. Savers aged 65 and older currently enjoy income-splitting options and the federal pension income tax credit on RRIF withdrawals — benefits that do not automatically apply to regular RRSP disbursements. Financial analysts expect these provisions to be integrated, though the budget text does not explicitly confirm their extension.
Broader reactions to the budget span multiple sectors. While the broader spending plan — detailed by CBC, allocates billions toward housing, affordability, and business investments like the Scientific Research and Experimental Development tax incentive, critics have raised concerns. The Bloc Québécois argued the budget neglects seniors' healthcare needs, while the Canadian Federation of Independent Business expressed disappointment over small business provisions.
Canadians should not expect immediate changes. The federal government’s proposal currently serves as an expression of intent, requiring extensive amendments to both federal and provincial legislation. Public consultations are open, and submissions are accepted by the Department of Finance until January 8, 2027. Savers and advisors alike must navigate current rules while awaiting technical regulations and implementation timelines.
How significant is this development?
Contribute your assessment to the aggregated reader sentiment ledger.
Frequently Asked Questions
Key questions answered in this reportWhat is the key development in: Canada proposes RRSP-for-life plan to eliminate RRIF conversion rules?
Budget 2026 introduces an innovative RRSP-for-life model designed to eliminate mandatory RRIF conversions, merging retirement accounts into a single continuous vehicle.
Why is this Business development significant for the UK?
This report covers critical events in our Business beat. Independent reporting monitors related UK statements, regulatory shifts, and public responses as further verified details emerge.
How was this reporting corroborated and verified?
Newsarchy UK compiles and cross-references reporting from primary reporting from CBC and cross-checked wire reports. All coverage adheres to published editorial standards.
When was this report published?
This briefing was published on November 7, 2026 and is permanently cataloged in the Newsarchy UK Business archives.