UK woman buys home at 25 on 27k salary using shared ownership scheme
A 25-year-old local government officer successfully purchased a home independently on a modest salary by utilizing a shared ownership scheme and a Lifetime ISA.
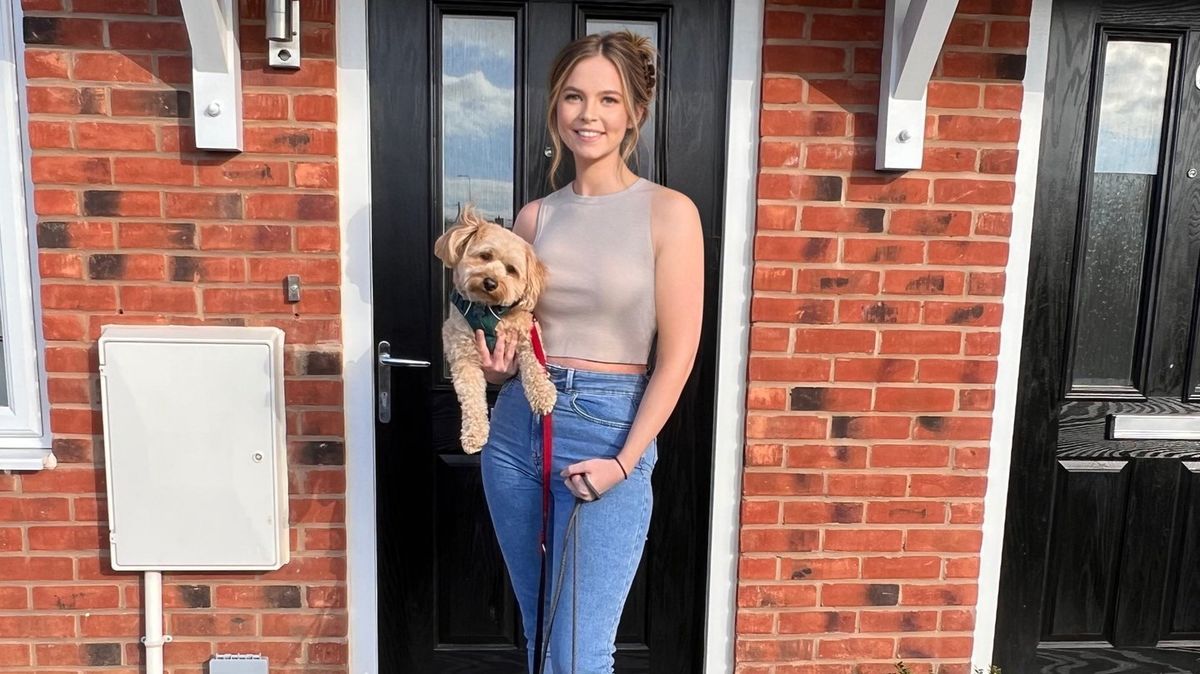
Securing property independence as a solo buyer demands immense personal sacrifice, yet alternative pathways are offering fresh routes onto the property ladder amidst ongoing cost of living pressures.
Buying a home independently remains a formidable challenge amid broader cost of living challenges and shifting market pressures, but alternative pathways are helping select buyers achieve independence earlier. Layla Phillips successfully purchased a house independently at age 25 while earning a modest salary, according to reporting.
Media additions

Phillips utilized the shared ownership model to secure a 25 percent share of a property valued at £265,000. She chose this route because her salary would otherwise have precluded a standard mortgage for a house with a garden suitable for her dogs. By entering shared ownership, she pays a modest mortgage alongside a reduced rent to the housing association for the remaining equity. She noted that without the scheme, acquiring a home independently would have taken several additional years.
Her saving strategy began during the Covid pandemic while earning a lower wage and living with her parents. Contributing a minimal amount toward household bills enabled her to maximize savings with the assistance of a government Lifetime ISA. By cutting unnecessary expenditures, she accumulated funds for a deposit alongside fees for solicitors and furnishings before completing the purchase.
Historically, securing a property at a young age typically relied on joint incomes or external financial backing. Previous reporting outlined how various young couples successfully navigated property purchases using different mortgage assistance frameworks, such as the former Help to Buy scheme. Those buyers similarly emphasized strict budgeting, lifestyle restrictions, and taking on extra shifts to accumulate deposits.
However, analysts and homeowners alike note that solo purchasing presents distinct hurdles. While partnered buyers often pool their resources to meet affordability criteria, individual buyers must navigate stricter lending caps relative to single incomes.
| Buyer Profile | Age | Salary | Property Share / Type | Method / Scheme |
|---|---|---|---|---|
| Layla Phillips | 25 | £27,000 | 25% share of a £265,000 house | Shared Ownership & Lifetime ISA |
| Mark Hepburn & Partner | 23 | £18,500 | Three-bedroom semi-detached | 5% deposit & Help to Buy |
| Andrew Douglas & Partner | 23 | £31,000 | Two-storey terraced house | Thrifty saving & joint income |
The divergence between solo and joint buyers underscores ongoing debates around housing accessibility. For many young people, homeownership feels like a distant dream, particularly as landlords push up rental prices and energy bills soar during the winter. Previous young buyers highlighted similarly described renting as dead money, pushing them to adopt strict budgeting measures such as swapping branded goods for supermarket budget items and cutting back on holidays.
According to ONS, Department for Communities and Local Government, and Land Registry data cited in reporting, the average price of a UK home reached £217,928 in November 2016, marking a 6.7 percent increase from the previous year. Furthermore, lender Halifax noted that the average age of a first-time buyer in the UK is 30, with the median income for a first-time buyer household in England standing at £43,000. Nearly a third had help from friends and family for their deposit, contrasting sharply with solo buyers navigating the market entirely on individual earnings.
Future Plans and Milestones
- Buyers utilizing shared ownership frequently target a five-year window to increase their equity stake through staircasing.
- Alternatively, homeowners may choose to sell their initial shared equity property to transition entirely onto the open market.
- First-time buyers continue to monitor evolving lending criteria and potential updates to government-backed property schemes.