iAccess Alpha Virtual Best Ideas Fall Investment Conference Begins Today
The iAccess Alpha Virtual Best Ideas Fall Investment Conference has commenced, bringing small and microcap firms together as global markets navigate energy shocks and central bank decisions.

The iAccess Alpha Virtual Best Ideas Fall Investment Conference commenced on Tuesday, September 15, 2026, bringing together small and microcap public companies and engaged investors for a two-day schedule of live-streamed corporate presentations and curated one-on-one meetings. According to event organizers, the opening day featured back-to-back webcasts from participating firms spanning multiple sectors, including biotech developers, aircraft manufacturers, security providers, and data center operators. Wednesday transitions entirely into pre-qualified management meetings designed to facilitate direct dialogue between corporate executives and institutional participants.
This virtual corporate showcase unfolds against a tumultuous backdrop across international exchanges, where broader equity markets navigate intense volatility driven by shifting energy supplies, central bank policy expectations, and sudden technology sector corrections. According to reporting from CNBC and Livemint, major indices across Asia and the West experienced choppy sessions as investors weighed escalating geopolitical conflicts against looming monetary decisions.
Media additions

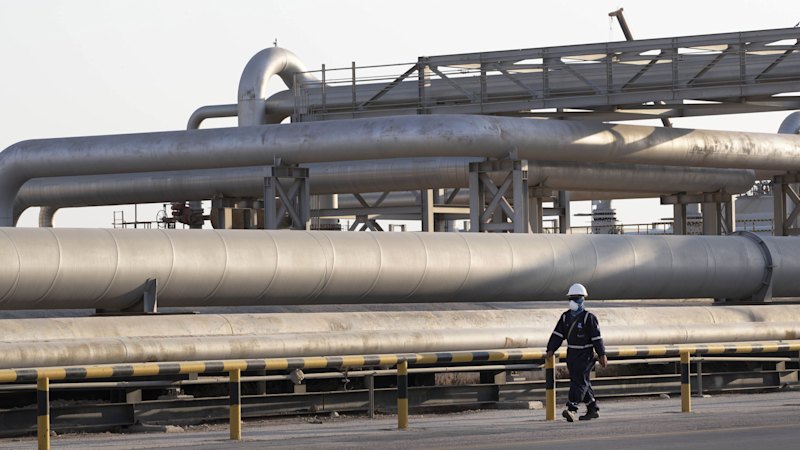
Energy markets reacted sharply to physical infrastructure disruptions in the Middle East. Streamlinefeed reported that Brent crude and West Texas Intermediate pushed higher after Saudi Arabia shut its East-West pipeline following a drone attack. This critical closure removed an alternative export route that allowed shipments to bypass the Strait of Hormuz during the ongoing conflict involving Iran. Livemint noted that international benchmark Brent crude climbed significantly compared to pre-war levels, while U.S. West Texas Intermediate also gained ground. Concurrently, Iran-backed forces reportedly seized strategic island and port locations along key Red Sea shipping lanes, intensifying global supply fears.
These energy spikes cascaded directly into macroeconomic indicators and monetary policy expectations. Streamlinefeed and Livemint highlighted that rising commodity costs fueled renewed inflation concerns, altering trader calculations ahead of central bank meetings. In the United States, the Federal Reserve began a two-day meeting on Tuesday, September 15, 2026, with its policy decision scheduled for Wednesday, September 16, 2026. Market expectations shifted following higher-than-expected inflation data, with CME FedWatch figures pointing to high probabilities of a quarter-point rate increase. FOMC minutes from previous sessions indicated that central bank officials viewed inflation risks as skewed to the upside due to regional conflicts.
The resulting macroeconomic cross-currents produced stark divergences across asset classes and regional exchanges. As reported by CNBC, Asian markets traded mixed. Japan's Nikkei 225 index closed lower in choppy trading following government data showing a year-on-year drop in exports amidst U.S. Tariffs and slowing external demand. Singaporean non-oil domestic exports plunged sharply, missing consensus forecasts due to falling demand in specialized machinery and petrochemicals. Conversely, Hong Kong's Hang Seng index climbed, bolstered by major corporate financing and technology tie-ups.
Australian markets reflected similar sector-level friction. According to The Motley Fool Australia and Streamlinefeed, the S&P/ASX 200 index faced downward pressure from retreating mining heavyweights such as BHP, Rio Tinto, and Fortescue, even as resource shares found support from surging oil and gold prices. Bell Potter analysts adjusted ratings across local equities, upgrading retail jewellery holdings on attractive valuations while maintaining recommendations on wealth management firms following corporate acquisitions.
Meanwhile, technology equities experienced severe downward pressure across global trading floors. Coinpaper reported that software and technology counters faced intense selling pressure driven by investor anxiety over artificial intelligence reshaping traditional pricing power and business models. These fears intensified following commentary from prominent technology executives in the United States calling for a slower pace in developing advanced artificial intelligence systems. Consequently, software valuations compressed sharply, with major technology listings touching multi-year lows as market participants reassessed high-multiple earnings premiums.
| Market / Index | Session Trend | Primary Driver |
|---|---|---|
| U.S. S&P 500 / Dow Jones | Cautious / Lower | Profit-taking and defensive positioning ahead of Federal Reserve monetary policy decisions |
| ASX 200 Resources & Energy | Resilient / Higher | Elevated crude oil and commodity prices offsetting broader index drag |
| Global Technology Sector | Sharp Decline | Investor anxiety over artificial intelligence disruption and software pricing power |
Financial analysts continue to parse the implications of these overlapping shocks. Livemint noted commentary from market researchers pointing to crucial technical support and resistance levels across benchmark indices like the Nifty and the Dow Jones as short-term profit-taking unfolded. At the same time, UBS strategists observed that surging bond yields—with U.S. And Australian multi-year yields testing previous highs—continue to cap the broader equity outlook and favor corporate price-makers over price-takers.
What happens next depends on the official outcomes of central bank deliberations and the physical security of international energy corridors. Investors will closely monitor the Federal Reserve's rate announcement, subsequent monetary policy commentary, and ongoing developments regarding Middle Eastern pipeline repairs. Meanwhile, presenting management teams at the iAccess Alpha Virtual Best Ideas Fall Investment Conference will conclude their scheduled one-on-one investor meetings through the remainder of the week.