Australia bans card payment surcharges from October 1: Here's What the RBA changes mean
Australia is eliminating debit and credit card payment surcharges nationwide in a sweeping Reserve Bank of Australia overhaul expected to save shoppers billions.
- Core Development: Australia is eliminating debit and credit card payment surcharges nationwide in a sweeping Reserve Bank of Australia overhaul expected to save shoppers billions.
- Beat Context: Categorized under Business with independent corroboration.
- Reporting Depth: 3 minute analytical read synthesized from verified newsroom sources.
Australia is eliminating card payment surcharges on debit and credit cards, altering retail transactions nationwide as part of sweeping Reserve Bank of Australia reforms. Under the new rules, the price displayed on a shelf or menu will be the exact total paid by the shopper, removing unexpected checkout additions that typically ranged from one to two percent. Networks including eftpos, Mastercard, Visa, and American Express are included in the shift, alongside aligned networks such as JCB and UnionPay, according to reports from The News and CommBank.
The regulatory overhaul follows an extensive review by the central bank, which concluded that the existing surcharging framework was no longer working as intended. According to Abc reporting, RBA Governor Michele Bullock noted that surcharges had become harder for everyday shoppers to avoid. Public surveys indicated widespread frustration with checkout fees, leading the central bank to implement the changes to restore pricing transparency. Additional oversight requires networks such as eftpos, Mastercard, and Visa to publish their merchant fees so businesses can compare rates more easily.
Media additions
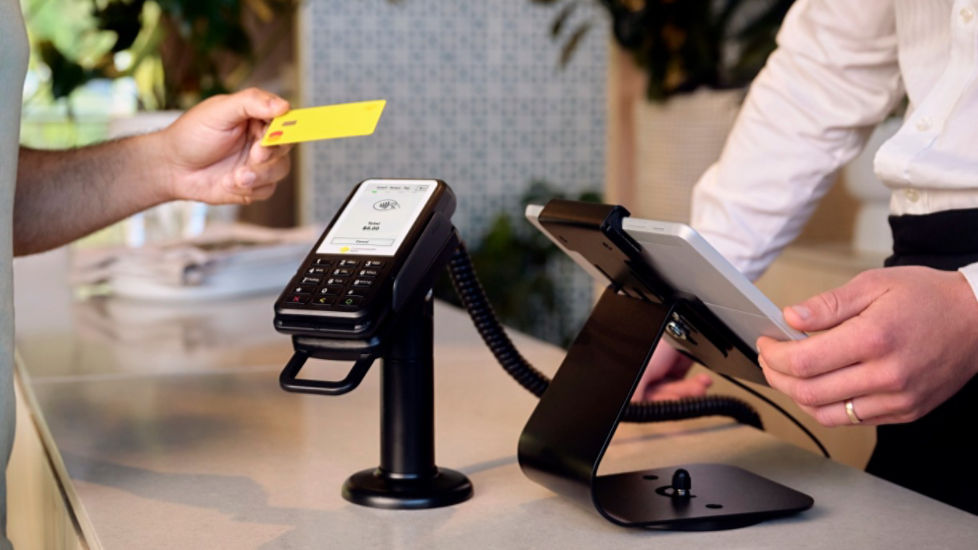

For merchants, the transition requires operational adjustments. CommBank notes that approximately sixteen per cent of businesses collected card surcharges prior to the federal announcement. To assist merchants managing payment acceptance costs, the bank announced it is reducing its Merchant Service Fee for in-store transactions on simple rate flat pricing to 0.99 per cent. For businesses on interchange-plus pricing models, merchant fees will automatically adjust to reflect the revised interchange caps.
The financial impact of the reforms extends across the banking and retail sectors. Finder research highlighted by Nine indicates that domestic credit and debit card purchases reached hundreds of billions of dollars prior to the reform. With banks facing millions in reduced annual revenue from lower interchange fees, major lenders have restructured consumer credit cards. Changes include higher annual fees, reduced reward earn rates, and shortened interest-free periods.
| Reform Metric / Area | Previous Structure | New Standard / Cap |
|---|---|---|
| Credit Card Interchange Fee | 0.8% of purchase value | 0.3% of purchase value |
| Consumer Debit Card Interchange Fee | 0.2% or 10 cents | 0.16% or 8 cents |
| Foreign-Issued Card Interchange | Varying legacy rates | Capped from April 1, 2027 |
Industry bodies have expressed mixed reactions to the transition. Meanwhile, small business advocates cautioned that businesses operating on tight profit margins face difficult choices between absorbing the costs or adjusting baseline menu prices, as noted by The Conversation.
Consumers accustomed to chasing reward points must also navigate a shifting landscape. The Sydney Morning Herald outlines how major issuers have pared back sign-up bonus offers, raised minimum spend hurdles, and trimmed complimentary travel insurance protections. These adjustments reflect how financial institutions are recovering lost revenue streams previously funded by interchange fees.
The transition arrives alongside broader shifts in consumer habits. Experts suggest that removing card surcharges may accelerate the ongoing decline of physical currency, as shoppers who previously used cash specifically to avoid checkout fees find fewer financial incentives to do so. Further regulatory scrutiny is anticipated as consultations regarding buy-now-pay-later providers progress, with additional foreign-issued card interchange caps scheduled to take effect in April 2027.
Ahead of the October 1 deadline, the Reserve Bank of Australia conducted an eighteen-month review of the payment system involving numerous submissions and stakeholder meetings.
How significant is this development?
Contribute your assessment to the aggregated reader sentiment ledger.
Frequently Asked Questions
Key questions answered in this reportWhat is the key development in: Australia bans card payment surcharges from October 1: Here's What the RBA changes mean?
Australia is eliminating debit and credit card payment surcharges nationwide in a sweeping Reserve Bank of Australia overhaul expected to save shoppers billions.
Why is this Business development significant for the UK?
This report covers critical events in our Business beat. Independent reporting monitors related UK statements, regulatory shifts, and public responses as further verified details emerge.
How was this reporting corroborated and verified?
Newsarchy UK compiles and cross-references reporting from primary reporting from Canstar and cross-checked wire reports. All coverage adheres to published editorial standards.
When was this report published?
This briefing was published on September 21, 2026 and is permanently cataloged in the Newsarchy UK Business archives.